


Investment Strategies
For “Quant” Investors, AI Is A Major Advance, With Caveats – Lazard AM
We talk to one of the portfolio managers at New York-headquartered Lazard Asset Management about the ways that AI affects the quantitative investment approach, pointing to the risks and opportunities.
AI has cut barriers to entry for the wealth sector's number crunchers trying to spot lucrative investment opportunities amid the data "fog."
This technology appears at first glance to be a harmonious match for the quantitative approach to investing, a style that draws on vast troves of data. "Quants" use mathematical models, statistical analysis, and computer algorithms to select securities and build portfolios.
Artificial intelligence enables quant strategists to test hypotheses faster, which is important in rapidly shifting markets, and it can extract information from previously hard-to-reach areas. On the downside, users must distinguish what large language models (LLMs) have uncovered from what they have memorized; they must also watch for AI's tendency to identify patterns that don't exist.
These are some of the observations from Kurt Livermore (pictured below), portfolio manager at Lazard Asset Management, part of Lazard. He spoke recently to Family Wealth Report. Livermore is based in Boston.
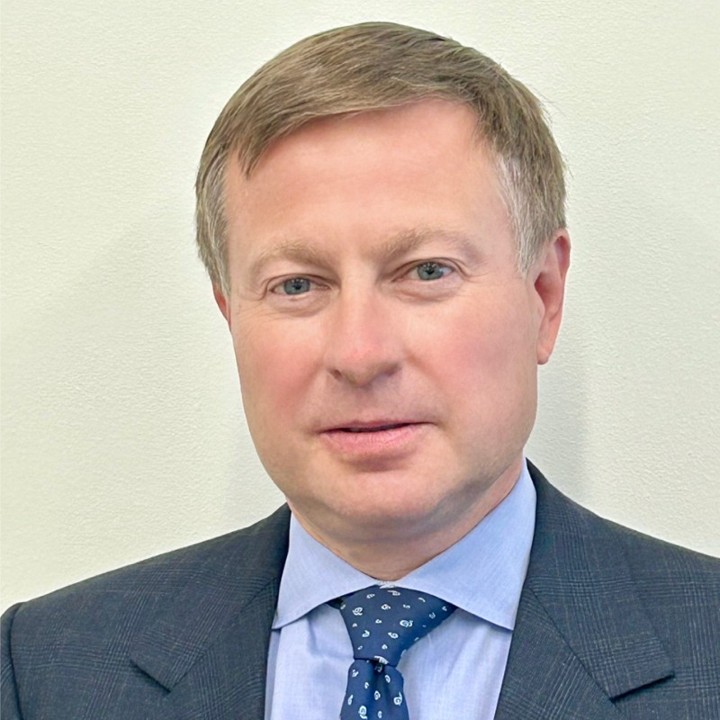
Kurt Livermore
FWR asked Livermore what wealth managers make of how asset managers use AI.
"In the wealth channel, the conversation is robust. There is a great deal of interest, but 'AI' is often used as a single undifferentiated label covering everything from a chatbot to a fully autonomous stock-picker. Much of our effort with private banks, family offices and RIAs is therefore definitional: distinguishing AI as a research tool within a disciplined process from AI as a black box, explaining why we insist on an economic rationale for every signal, and giving them the questions to ask any manager, including us," he said. "Transparency about what the tools do and do not do has generated the most interesting conversations."
His views carry the weight of a business that, as of March 31 this year, had total AuM of $259 billion across the Lazard group, according to results issued May 1.
Where has AI proven to be particularly
useful?
"Our starting premise is that markets are very good at pricing
information that is simple and widely observed, and much less
good at pricing phenomena that are complex, embedded in networks,
or absent from standard financial datasets," Livermore said. "The
data is rarely hidden; most of it is public. The difficulty is
that making sense of it requires connecting many weak, dispersed
pieces of evidence across companies, sources, and time. That is
precisely the kind of information markets absorb slowly.
"Every piece of research begins with a question about why a particular kind of structural information might be mispriced. Someone on the team articulates the mechanism: a company's position in a patent-citation network, intangible investment that accounting rules force firms to expense, the heterogeneous way a macro shock transmits through supply chains.
"We write down what we expect to see and what would falsify it before touching the data. Then the hypothesis is tested, including on how slowly its edge fades after a portfolio is formed. That decay profile is diagnostic: a signal capturing genuine structural information should lose strength slowly; a signal capturing something transient fades quickly. If the result doesn't behave the way the hypothesis predicts, it doesn't enter the model. The reason we insist on the hypothesis first is that the alternative, letting the data generate the idea, is where most spurious results come from. With enough variables you will always find something that 'worked.' Requiring an economic rationale is our main defense against that."
Livermore has worked as a quant portfolio manager for almost 30 years. He began his career in San Francisco, working at various firms, and joined Lazard Asset Management three years ago.
The large toolkit
Quants use AI in various ways. This news service, appropriately
enough, used an AI search to bring up examples. These include
machine-learning return prediction, used at firms such as
Renaissance Technologies, D E Shaw and Two Sigma; natural
language processing, in which earnings call transcripts,
regulatory filings, news and other communications are scored for
sentiment, tone and changes in vocabulary to feed trading
signals; alternative data processing, such as using satellite
imagery, web traffic and shipping data to gain insights into
financial behavior; and analyzing portfolio risks and
correlations, among others.
Livermore said productivity is a big plus from AI.
"These tools write usable, robust code quickly, and that has changed the economics of research. The constraint has moved more in the direction of good ideas; the time it took to turn an idea into a clean, tested implementation is much shorter. When that cycle shortens from weeks to days, we can test more hypotheses, kill the weak ones sooner, and spend more of the team's time on the question of why something should work rather than on the plumbing," he said.
The "reach" of AI is another advantage.
"The tools extract usable information from text we previously treated as too noisy to use systematically. Something a human could do for one company in an afternoon can be done for an entire universe overnight, and done consistently," he said.
And the negatives?
"The first [negative] is how easily the tools will give you a confident, well-fitted answer to the wrong question. The capacity to find patterns is also a capacity to find patterns that aren't there, and we have had results that looked compelling in-sample and dissolved on contact with new data," Livermore said. "The second is subtler and more dangerous for a backtest-driven discipline: it is hard to separate what an LLM has uncovered from what it has memorized. A language model trained on text up to a given date has, in effect, read the newspaper for every year in your backtest."
Today's market volatility can be overstated when set against previous episodes, but the drama of daily headlines can still be unsettling. FWR asked Livermore how AI helps quants navigate such conditions.
"In volatile periods the information flow accelerates and the value of being able to process it quickly and dispassionately rises. Systematic processes do not panic, and that is an advantage," he said. "The caveat is that models trained predominantly on calmer regimes can be at their least reliable precisely when conditions change. So, our approach is not to let the tools run harder in a crisis but to lean more heavily on the risk framework and on human oversight of what the signals are telling us and why."
What happens to returns?
"Judging the difference AI tools make to returns in any specific environment is difficult, and I would be cautious about any claim that puts a number on it. A tool's contribution cannot be separated cleanly from the signals it helped build, the risk framework around them, and market conditions themselves, and the period over which these tools have been in use is too short to draw conclusions," Livermore said.
There are various claims made about how well AI-powered investments fare. For example, in 2025, a report (aistreet.beehiiv.com, March 2025, Bloomberg) said Bridgewater Associates' $2 billion AI fund is, in the words of its CEO Nir Bar Dea, generating "unique alpha that is uncorrelated to what our humans do.” The article did not disclose specific figures. Run by co-CIO Greg Jensen, the fund combines Bridgewater's proprietary technology with plans to include models from OpenAI, Anthropic, and Perplexity. Bridgewater formed its Artificial Investment Associate (AIA) Labs division in 2023.
In another case, that of M&G (Lux) Global Maxima Fund, M&G was quoted saying in February 2025 that this portfolio, which blends AI stock-picking recommendations with human oversight, beat its benchmark, the MSCI ACWI Net Return Index, over the five years from inception.
In general, however, it appears that while results from some cases appear promising, it may be premature to uncork the champagne just yet.
Kill or cure?
There is also the open question of whether AI is part of the
volatility story as well as a way of handling it.
"I'd stress this is a hypothesis rather than something we can demonstrate. If many investors interpret the same event through similar tools, they may reach similar conclusions at similar times, which could in principle amplify market moves rather than dampen them. That concern would be greatest where users lack the expertise to evaluate the output and defer to it rather than to their own judgment. Whether any of today's volatility reflects this, we can't say. It is one more reason [why] we view AI as a tool for testing hypotheses that can be defended on their own terms, rather than as a source of market views," Livermore said.
Looking ahead, Livermore predicted that "nearly every manager will describe itself as using AI, so the label will stop differentiating and process discipline will matter more."
He argued that easily replicated applications, such as asking an AI tool which stocks to buy, will see whatever edge they have decay quickly as they become commoditized; the durable advantages will sit in proprietary ideas, in how signals are combined, and in how the research function is organized.
"The research cycle continues to compress. That is a productivity gain, but it also raises the risk of explaining the past perfectly and predicting nothing, so the firms that benefit will be those that tighten their testing standards as throughput rises rather than relaxing them," he said. "I expect the winning model to be collaboration: humans generating and judging hypotheses, machines testing them at a scale that was not previously possible."